A watchdog report says Michigan mosques let a Senate candidate solicit support from the pulpit, raising clear questions under federal tax law.
Story Snapshot
- Federal tax law bans tax-exempt charities, including mosques, from backing candidates.
- A report names a Dearborn Heights imam who urged congregants to vote for Abdul El-Sayed.
- Guidance flags pulpit endorsements and on-site campaign activity as potential violations.
- No public record shows an Internal Revenue Service investigation or finding so far.
What The Watchdog Report Describes Happened Inside Mosques
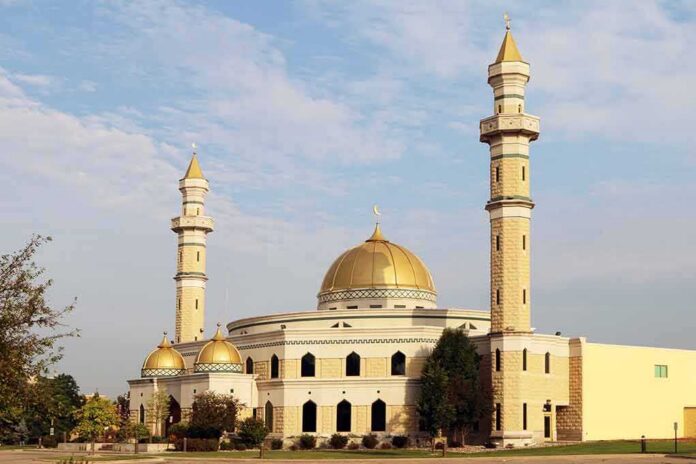
The Middle East Forum says multiple Michigan mosques gave Abdul El-Sayed a pulpit during Ramadan prayers and let him solicit signatures to qualify for the Democratic primary ballot. The report quotes Imam Mohammad Ali Elahi at the Islamic House of Wisdom urging congregants to “vote for Brother Abdul El-Sayed.” It frames the conduct as direct campaign activity inside religious services. The report names institutions, a cleric, and a candidate, which makes the claim specific and checkable.
The same report says an imam welcomed El-Sayed during worship and encouraged congregants to support him. It also says signature gathering took place with mosque access and encouragement. These details matter legally because they involve a named venue, a named religious leader, and a clear election ask. The account does not include a full public video record in the provided materials. Still, the cited statements are concrete enough to trigger policy and legal review questions.
What Federal Tax Law Allows And Prohibits For Religious Charities
The Internal Revenue Service states that section 501(c)(3) charities, including churches, synagogues, and mosques, cannot directly or indirectly intervene in any political campaign. The rule bans endorsements, opposition, fundraising for candidates, and using organizational resources to favor any candidate for public office. The restriction applies to federal, state, and local races. The agency explains that staff, facilities, and official communications may not be used to support a candidate.
The Internal Revenue Service training materials list risky actions, such as pulpit endorsements, asking people to vote for a candidate, or letting campaign activity occur during official events. The agency also notes some limited, neutral forums are allowed if all candidates get equal access and the organization stays nonpartisan. Equal time, no fundraising, and neutral messaging are key factors in those settings. Any shift toward support or opposition to a named candidate can cross the line into prohibited intervention.
Why The Allegations Matter For Enforcement And Public Trust
Americans of all views expect the tax code to apply fairly. If any tax-exempt group, religious or not, uses its platform to back a candidate, it can gain an unfair edge. That problem angers conservatives who see selective enforcement against churches, and it worries liberals who fear dark corners where politics hides from public rules. The rule aims to keep faith and charity work from becoming campaign machines paid for with tax breaks.
Past reviews show the Internal Revenue Service rarely brings the harshest penalties. Guidance and case summaries describe investigations but few revocations. That history fuels a sense that the powerful get passes while regular people play by strict rules. Clear, even-handed enforcement would help rebuild trust. Applied fairly, the same standard should cover sermons, speeches, mailers, and stage time across all faiths and causes.
What We Do Not Know Yet And What Would Clarify The Record
The watchdog report does not itself prove the exact tax status of every mosque involved. The Internal Revenue Code’s ban applies to section 501(c)(3) organizations, and some entities may have other legal forms. Public records like Internal Revenue Service determination letters and state filings would confirm status. Event details would also matter, such as whether other candidates were invited on equal terms or whether neutrality statements were read during the services.
No public Internal Revenue Service finding appears in the provided materials. That leaves open whether the agency will review the conduct or issue guidance to the institutions named. The most straight path forward would include authentic event videos, transcripts, and facility-use policies, plus campaign and venue correspondence. Those materials would show if the events were neutral forums or partisan interventions as the Internal Revenue Service defines them.
How This Fits A Broader, Repeating Pattern
These questions are not new or unique to one faith. The campaign-intervention ban dates to 1954 and covers all charities. Government reports and academic reviews describe recurring cases and guidance reminders. The theme is the same: the legal rule is clear, but each case turns on facts like tone, timing, location, and whether the institution used its resources to back a candidate. Formal penalties remain uncommon even when reviews find some improper activity.
For citizens, the takeaway is simple. If a tax-exempt charity backs a candidate from its official platform, it risks its status. If a charity hosts candidates on equal terms without endorsements, it stays inside the rules. The Michigan report, if accurate, describes activity that squarely raises these issues. The Internal Revenue Service’s next steps, or lack of them, will signal how seriously the government treats these lines in a heated election year.